
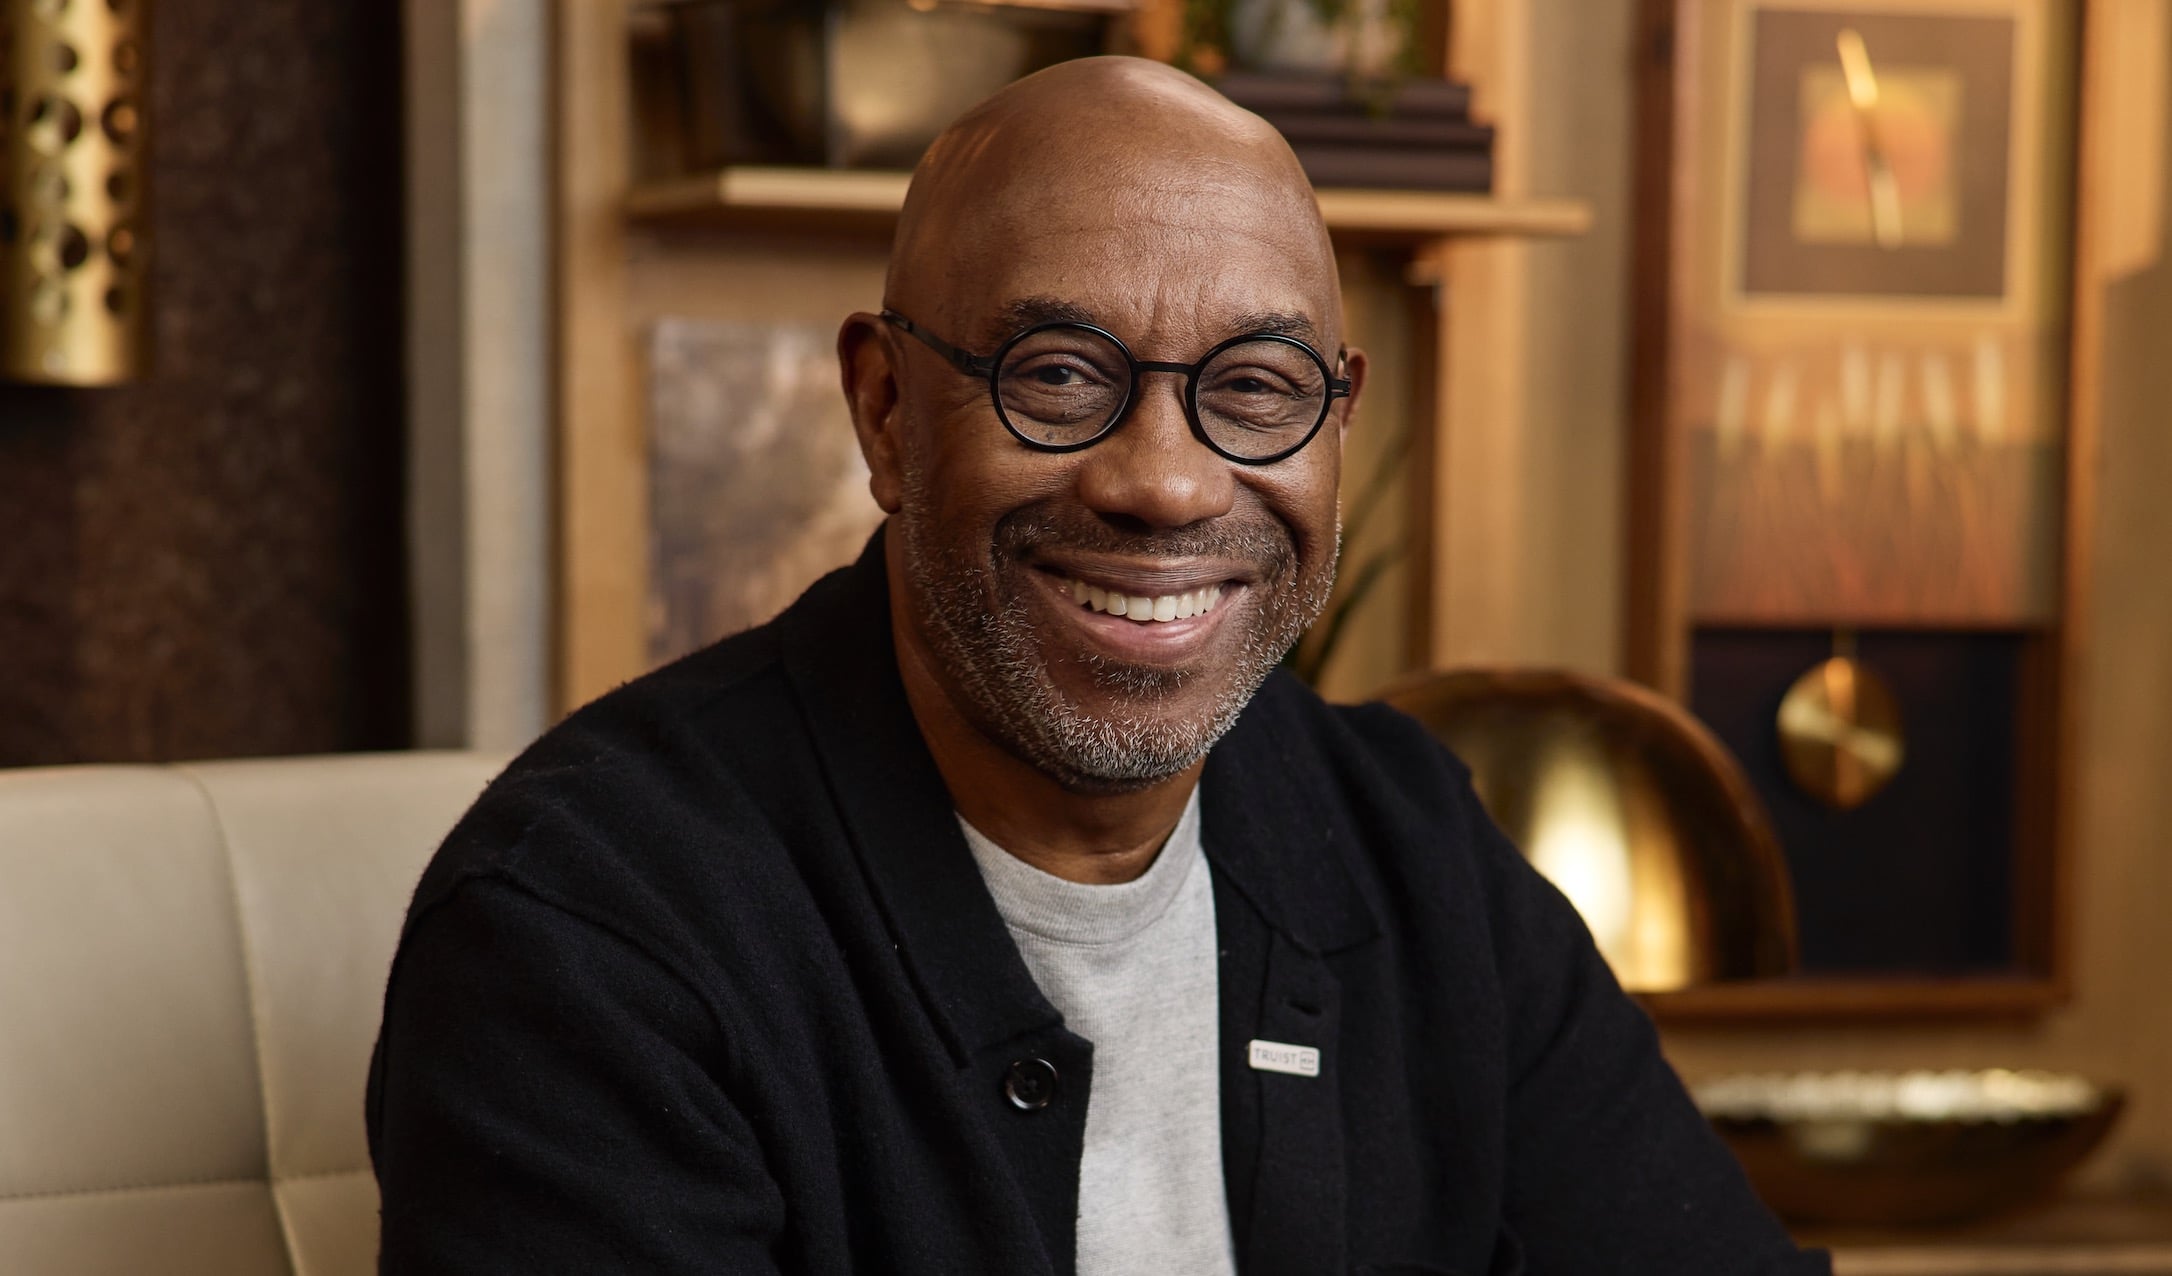
Charles “CJ” Johnson, head of entertainment investment banking at Truist Securities, says public markets price music companies on quarterly results, while catalog buyers price long-term royalty income. His view comes as a string of large deals has reshaped the independent music sector this year.
Truist’s record in music rights financing#
Johnson and his team have worked on financing for Kobalt, Litmus Music, Lyric Capital, Influence Media Partners and Create Music Group. Recent transactions include the following.
- Left-lead arranger on Kobalt’s USD $450 million revolving credit facility, and joint bookrunner on the publisher’s $266.5 million asset-backed securitization in 2024, two years before Primary Wave agreed to acquire Kobalt.
- Left-lead arranger and lead bookrunner when the revolving credit facility of Litmus Music was upsized from $250 million to $400 million in July 2024. Litmus used the funds to buy Opus Music Group.
- Lead on the debt financing and financial advisor to Influence Media Partners on its $600 million-plus deal to buy Anthem Entertainment’s catalogs, which is due to close in the fourth quarter.
Truist’s entertainment investment banking practice dates to 2009. Its private wealth sports and entertainment arm goes back four decades and at one point traded under the name the Official Bank of Music, Johnson noted on the bank’s Navigating Beyond the Expected podcast.

Consolidation and catalog pricing#
Johnson said the year has substantially reorganized the independent sector. Three deals were announced within 50 days of each other this spring:
- Primary Wave’s acquisition of Kobalt
- The BMG-Concord merger
- Sony Music Publishing’s purchase of the catalog of Blackstone-owned Recognition Music Group
Together, the three transactions were worth more than $19 billion. Johnson says the market remains active, with intense competition at the top and discipline at the lower end. Iconic catalogs have stabilized in the mid to high teens, with no return to the 2021 peak.
Financial sponsors remain interested in the asset class, particularly when a potential acquisition involves an iconic catalog that adds or creates scale. In his view, the key bid-ask gap concerns whose multiple applies rather than the multiple itself. Broad-market publishing catalogs more than 10 years old typically clear at roughly 12 times, while truly iconic assets trade at premiums of 50% or more. Sellers often anchor to iconic-tier headline valuations, although most assets do not qualify for that tier.
“Today, that mismatch, not interest rates, is where deals are breaking down.”
Trends and investor interest#
Johnson identifies three trends:
- Concentration: By 2027, the three majors plus a combined BMG-Concord are expected to control roughly 75% of the publishing market.
- Geographic rotation: growth is shifting away from the United States and Western Europe toward India, South Korea, Latin America and the Gulf. Many conventional underwriting models do not yet fully account for these regions.
- AI licensing: artificial intelligence (AI) licensing has emerged as a real, though still unproven, revenue stream rather than simply a threat.
Given the number of companies that traded in 2026, investor focus may appear to have shifted from catalogs to operating platforms. Truist continues to see interest in the $5 million to $50 million purchase price range, where many new entrants are targeting the middle market.
Johnson says he often speaks with prospective investors who ask whether they are too late to enter the space. His answer:
“New music is created every day, and within it are songs, songwriters, and artists that may one day become iconic.”
AI licensing and public market valuations#
Over the past year, AI has been reframed from an existential threat to a licensing opportunity. Several major music companies have recently settled copyright disputes with AI platforms and entered into licensing agreements for new AI music models. Still, Johnson says the impact on valuations will not be applied evenly across the industry.
He says AI training and licensing income is largely a scale-driven payment stream, one that favors platforms with large, rights-verified catalogs over individual artists or smaller catalogs.
“AI-generated supply is flooding the low end of streaming and diluting per-stream economics for less-differentiated content.”
Johnson says this dynamic makes evergreen copyrights with genuine cultural attachment relatively scarcer and supports an iconic-tier premium. He cautions that no durable, disclosed rate card for AI training income exists yet, so treating it as a forecast line rather than optionality could be a mistake in this cycle.
Public and private markets can tell very different valuation stories, although the industry often compares them directly. Johnson notes that publicly traded music companies can trade at lower multiples, while high-quality catalogs can command significantly higher multiples in private transactions. Public-market multiples can also shift quickly when earnings or key growth metrics fall short of investor expectations. He describes the gap as rational.
Catalog multiples reflect relatively predictable, low-overhead royalty streams that function more like bonds with upside. Public label multiples, by contrast, value operating businesses exposed to A&R (artists and repertoire) risk, marketing spend and quarterly disclosure pressure.
In other words, public markets are pricing the quarter, not the catalog. That disconnect is also helping drive the 2026 consolidation wave, as strategic buyers can effectively acquire listed platforms.